
Articles
See All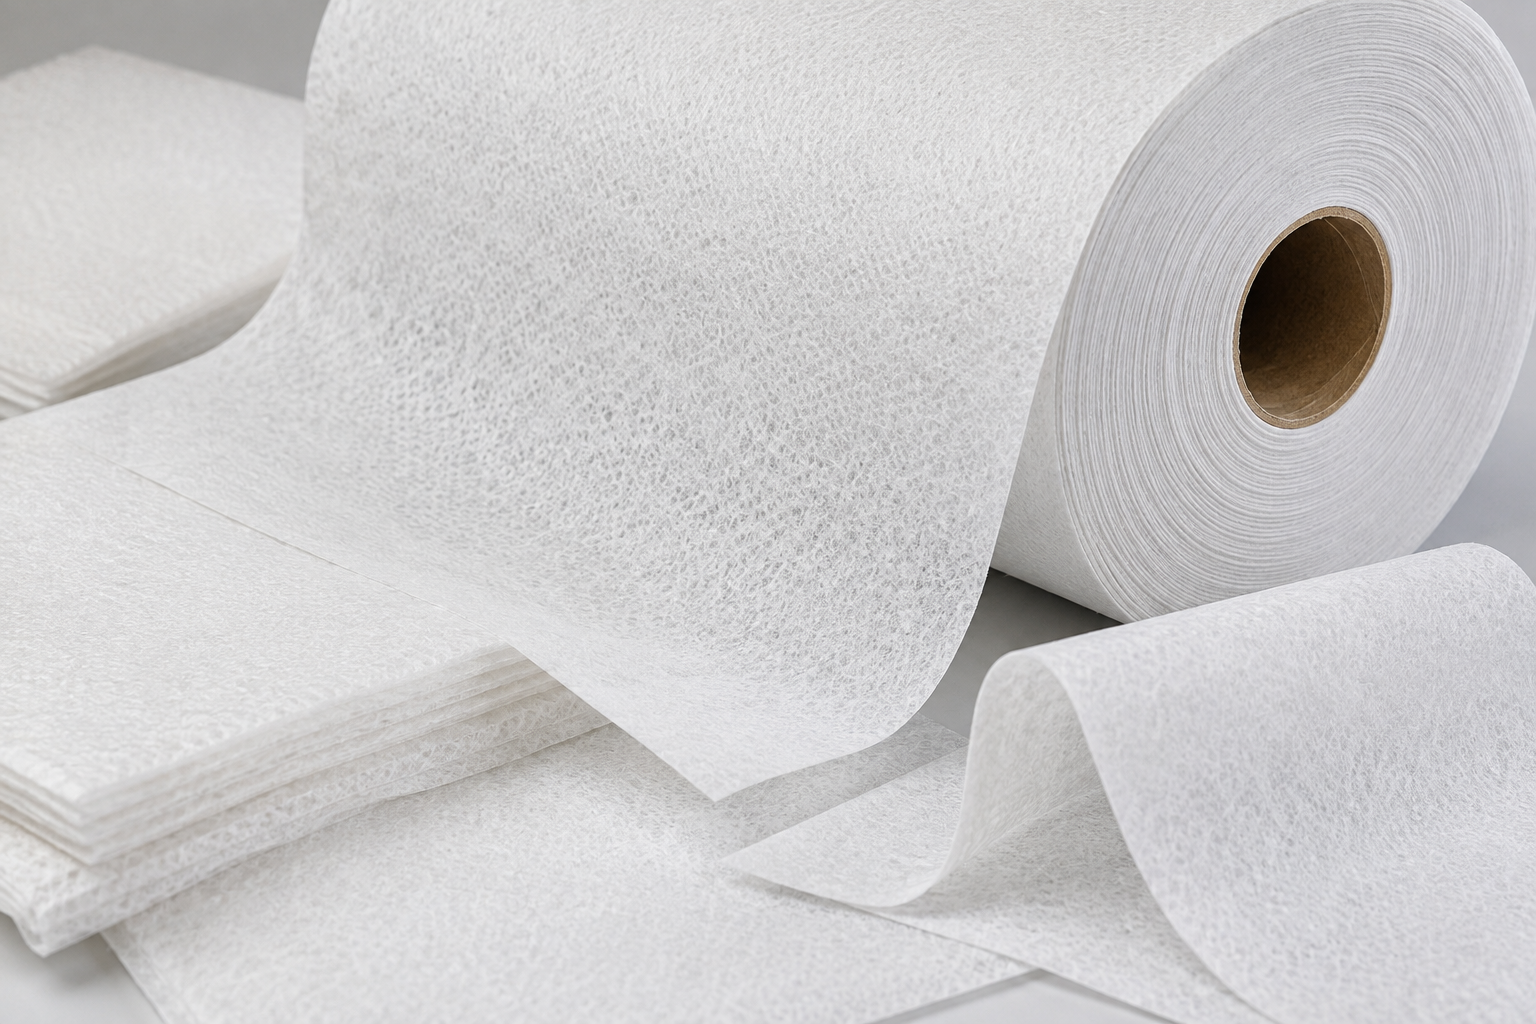
Micro-Cap Story · The Waiting Game
The WestBond Wake-Up
For years this little Canadian paper company did nothing. Then the margins turned — and a founder who owns a quarter of the stock finally had a tailwind at his back. Plus: the air-laid field it survives in, and the graveyard of juniors that didn’t.
WestBond Enterprises TSXV: WBE · OTC: WBNEF ~C$0.215 · mkt cap ~C$7.7M · As of Aug 2026
Part One · The Company
What WestBond makes, why it stalled for five years, and what just changed.
Let me tell you about the most boring company I’ve looked at all year. WestBond makes paper. Not the interesting kind — the disposable kind. Napkins. Patient wipes. The crinkly sheet the nurse pulls across the exam table before you sit down. Toilet paper for office buildings. If that already made your eyes glaze over, good — because that’s exactly why almost nobody is watching what just happened to the numbers.
Here’s the hook. This company spent the better part of five years going sideways. Sales in fiscal 2022: $11.4 million. Two years later, fiscal 2024: $9.2 million. It went backwards. It lost money — a $211,000 loss in 2024, another $52,000 loss in 2025. The kind of chart that makes you close the tab.
Then, in the year just ended (March 31, 2026), the tape flipped:
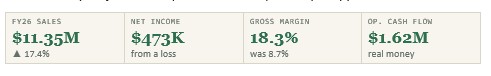
A swing from red to a $473,000 profit. Gross margin didn’t just tick up — it doubled off the 2024 bottom, from 8.7% to 18.3%. And it wasn’t one lumpy quarter: the very next quarter (to June 30, 2026) kept accelerating — sales up 6.3% to $2.9 million and net profit of $295,000 versus just $98,000 a year earlier. Roughly a triple. Margins that quarter pushed to about 25%.
This is the exact shape micro-cap investors wait years for: nothing, nothing, nothing… then the operating leverage finally kicks and the bottom line moves in a way the share price hasn’t caught up to yet.
The Paper Company That Makes Its Own Paper
Most ‘paper products’ companies are just converters — they buy giant rolls from a mill and cut, fold and package them. WestBond does something rarer. It runs its own air-laid paper machine and makes the raw material itself, then converts it into the finished product — one of only a handful of fully integrated air-laid converters in North America.
Why care? Because that machine is the whole story — the moat and the ceiling. On the moat side: WestBond controls its own supply chain, pulp in one end, finished napkins out the other. It’s so self-sufficient it sells its surplus raw air-laid rolls to other converters.
Its Competitors Literally Buy Their Raw Material
From WestBond.
The product mix breaks into four real lines. Fiscal 2026, ranked by revenue:
① Napkins & air-laid parent rolls — $4.68M (41% of sales, +22.6%). The crown jewel, and management flat-out says these converted napkins ‘carry higher margins than our other product lines.’ They replace linen in restaurants and let a restaurant use fewer napkins per guest — supplied to four national restaurant chains and two hotel chains, in white and champagne. Both the biggest line and the most profitable, which is why selling more of it lit up the whole income statement.
② Personal hygiene — $2.66M (23%, +30.4%). Toilet paper and towels for offices and institutions — the fastest grower of the year. The multinationals keep abandoning these low-glamour niches; WestBond keeps the high-margin scraps.
③ Wipes — $2.32M (20%, +1.7%). Compostable dry patient wipes for nursing homes and hospitals, plus a branded disinfectant wipe, ViroBan Plus. The COVID hero of 2020–21, now a steady healthcare staple with an aging-population tailwind.
④ Clinical — $1.66M (15%, +12.2%). Gowns, drapes, exam-table paper, waterproof underlays — the disposable paper in every doctor’s office, and the line the company was built on. Management calls it ‘very profitable and stable.’ Boring cash, the good kind.
Everything is now being pulled under one brand umbrella — ‘Medley’ — to make the catalogue easier to sell, including through newer channels like Amazon.
Why It Sat Dead For Five Years
You need to see the shape of the wait to appreciate the wake-up.
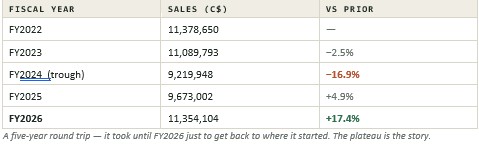
So why did a company with a real moat spend half a decade going nowhere? A few honest reasons, and they matter for what comes next.
It has one plant and essentially one paper machine, in Delta, B.C. Capacity is a hard ceiling. It grows out of its own pocket, plowing roughly $1 million of cash flow a year back into equipment rather than raising money or diluting shareholders. It runs on just 26 employees, and management repeatedly flags — in the filings — how hard it is to find and train skilled machine operators. And it’s a B2B outfit selling through distributors; there’s no viral consumer brand pulling it forward.
Add the boring-but-real stuff: one customer is more than 10% of sales, pulp is bought in U.S. dollars and can whip around, and contracts only let WestBond pass through paper-cost hikes up to about 10%. When input costs spiked in 2023–24, margins got crushed — that’s the trough in the table above.
What Actually Changed
The unlock wasn’t a new product or a splashy contract. It was mix. WestBond sold proportionally more of its highest-margin air-laid napkins — to those restaurant chains, and now to major American restaurant-supply distributors placing orders — and because the factory’s fixed costs were already there, almost every extra napkin dollar dropped toward the bottom line. Watch the gross margin climb:
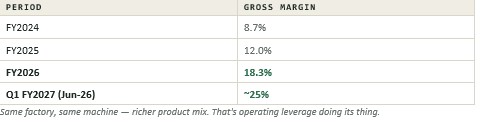
On a ~C$7.7 million market cap, the company just did $1.6 million of operating cash flow and $473K of net profit — and the most recent quarter says the trend is still pointing up, not reverting. That’s the whole reason this crinkly-paper company is worth ten minutes of your time.
The Founder Still Owns A Quarter Of It
This is the part I always want to know before anything else: who’s holding the stock, and do they eat their own cooking?
WestBond’s answer is about as aligned as micro-cap gets. Gennaro Magistrale has been CEO since October 1989 — he has run this company for 37 years — and he still owns 8.1 million shares, about 22.8% of the company. This isn’t a hired-gun team optimizing for a quarterly bonus; it’s a founder whose net worth rides on the same shares you’d be buying.
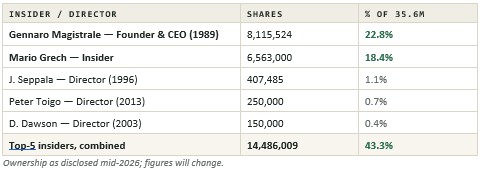
Two men — Magistrale and Grech — hold over 41% between them; insiders as a group control roughly 43% of the shares. That cuts both ways. The good edge: incentives nailed to the share price, basically no chance of reckless dilution, and only ~35.6 million shares out — a tight float where a real earnings turn is felt. The other edge: this is effectively a controlled company. No activist storms in to force a sale or a growth spurt. It moves at the founder’s pace.
Part Two · The Field
Who else makes air-laid paper —
and why nearly every small, listed player
that tried to scale it–got swallowed.
Air-laid is a specific way of making paper: instead of floating wood fibres in water (the way tissue is made), you lay them down with air and bond them. The result is thicker, softer, more absorbent — the stuff of premium napkins, patient wipes, feminine-hygiene cores and food pads. It sits in the nonwovens world, and the machines that make it cost tens of millions of dollars.
That price tag is the whole competitive story. Air-laid is dominated by a handful of billion-dollar industrial players, plus a few mid-size European specialists. Underneath them is a striking pattern: a small graveyard of junior, publicly-listed air-laid companies that tried to grow into the big leagues — and, one after another, got acquired or restructured out of existence. WestBond is the rare micro-cap still standing on its own. Here’s the field.
Who Else Makes Air-Laid Today
Ranked roughly by scale. ‘Overlap’ is how directly each competes with WestBond’s actual products — premium napkins, patient wipes, clinical paper, away-from-home hygiene.
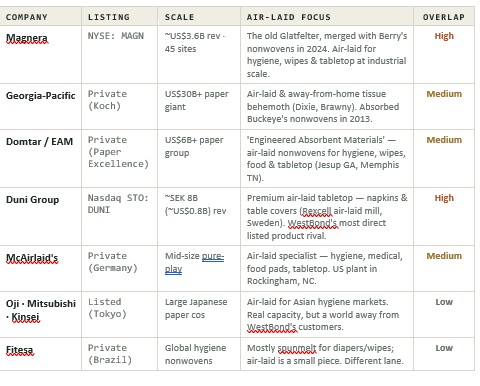
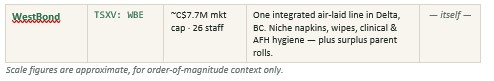
Look at the size gap. WestBond’s entire company is worth about C$7.7 million; Magnera does ~US$3.6 billion in revenue. WestBond isn’t fighting these giants head-on — it survives precisely by being too small to bother chasing, in niches (custom restaurant napkins, Canadian-made clinical paper) the majors have walked away from.
The one name to circle is Duni. It’s a listed European company built on exactly WestBond’s crown jewel — premium air-laid napkins and tabletop. The saving grace: Duni is overwhelmingly a European brand, so the two rarely meet on the same distributor’s shelf. But it’s proof the napkin niche can be scaled into a near-billion-dollar business.
The Air-Laid Junior Graveyard
If you want to judge WestBond against anything, judge it against the other juniors. There have been a few small, publicly-listed air-laid names — and their stories rhyme. Each grew, borrowed or expanded hard to reach industrial scale, and was ultimately absorbed by a bigger fish. This is the single most useful lens for judging WestBond.
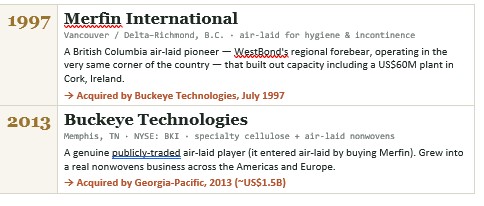
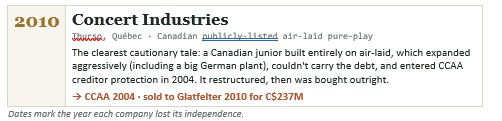
Notice what happened to the two Canadian juniors in particular. Concert borrowed and built to chase scale — and the balance sheet broke. Merfin, based in the very region WestBond calls home, scaled up (Ireland plant included) and was swallowed within a few years. Both were bigger and bolder than WestBond. Neither exists independently today.
The Survivor’s Read:
Where WestBond Actually Fits
Put the two parts together and WestBond’s ‘moat’ looks a little different — and, in a way, more interesting. It’s not that WestBond owns unique air-laid technology; the giants have far more of it. Its edge is a combination the big players can’t be bothered to copy and the juniors couldn’t survive without becoming: a tiny, fully-integrated, self-funded operation serving customized, low-volume, Canadian-made niches.
What genuinely protects it
● Too small to be a target. At a C$7.7M market cap serving niche accounts, WestBond isn’t worth a giant’s effort to displace — the volumes are beneath them.
● Integrated at micro-scale. Owning its own air-laid machine (rare for a company this size) means it controls supply and can sell surplus parent rolls — even to would-be rivals.
● ‘Made in Canada.’ Short lead times and domestic supply matter to Canadian healthcare and food-service buyers, especially amid U.S.–Canada tariff friction — a lane the U.S. giants can’t own.
● Debt discipline. The juniors that died reached for scale on borrowed money. WestBond self-funds ~C$1M/yr of equipment from cash flow and barely dilutes — the exact opposite of the Concert playbook.
Where the field still threatens it
● Scale economics. Magnera, GP and Domtar buy pulp and run machines at a scale WestBond can’t match — in a commodity-input business, that’s a permanent cost disadvantage, and it’s why WestBond can only pass through about 10% of an input spike.
● Duni in napkins. WestBond’s richest line is premium air-laid napkins — precisely Duni’s core. If Duni (or a giant) pushed harder into North American food-service, it would hit WestBond where it earns most.
● The takeout paradox. The same niche strength that keeps WestBond independent also makes it a plausible bolt-on for a larger converter one day — good for a shareholder on exit, but it means ‘staying small forever’ isn’t guaranteed either.
Part Three · The Scorecard
What To Track From Here, In Both Directions.
What I’m Watching From Here
I’m not here to tell you to buy it — do your own work, and this is a thin, illiquid name where a few thousand shares can move the price. But here’s the honest scorecard I’d keep on my desk, now with the competitive field folded in.
What could make it work
● The margin trend holds. If gross margin stays high-teens-to-20s as napkin volume grows, the earnings power is a large multiple of a ~C$7.7M market cap.
● U.S. napkin distributors scale up. Management says major American restaurant-supply distributors have started placing orders — the growth lever with the most room.
● ‘Made in Canada’ as a tailwind. Amid U.S.–Canada tariff noise, domestic, compostable, short-lead-time supply is suddenly a selling point, especially into healthcare.
● Self-funded expansion. A fresh ~C$3M Scotiabank facility (with equipment financing) is funding new, faster machines to lift the capacity ceiling — no dilution.
● Cheap on the surface. ~C$0.215 against ~C$0.23 book value per share — roughly paying book for a business that just turned profitable and cash-generative.
● The niche the majors abandoned. Every giant in the field has walked away from low-volume custom work. That vacated ground is the whole reason a 26-person company can hold a defensible position at all.
What could break it
● Pulp, the loonie, and no pricing power. Paper is priced in USD, and contracts cap pass-through at about 10%. A cost spike WestBond can’t fully pass through is exactly what caused the 2024 margin trough — and the giants can absorb one where it can’t.
● Customer concentration. Losing the one 10%-plus account would leave a visible dent.
● The capacity ceiling is real. One plant, one machine, 26 people. Growth is gated by equipment and by finding operators to run it.
● Controlled & illiquid. ~43% insider-held and thinly traded — it moves at the founder’s pace, and it can be hard to get in or out.
● Tariff escalation. Threatened tariffs of up to 50% and any unwind of USMCA exemptions could cut the other way.
● A bigger player wants the napkin niche. Duni already owns this product category in Europe. A push into North American food-service by Duni or a U.S. giant would land on WestBond’s most profitable line.
● The junior’s endgame. Merfin, Buckeye and Concert all reached for scale and lost independence. Reaching is the risk — but so is never reaching, if the capacity ceiling caps the story at roughly today’s size.
The one-line version: a boring, founder-run, cash-generating little paper company that spent five years asleep and just posted its best margins in memory — with management holding almost half the shares and no one on the Street paying attention.
The field around it is a big-company game with a graveyard of ambitious juniors behind it, and WestBond has survived 37 years not by winning that game but by refusing to play it. The risk isn’t that a giant crushes it tomorrow; it’s that the very qualities keeping it independent also cap how big it can ever become. Whether that’s an opportunity or a value trap comes down to one question you can now track quarter by quarter: does the margin hold?
NOTE–this story was written by me and my best friend Claude(AI)
Not investment advice. This is an educational story for retail investors, written in a first-person newsletter voice and compiled from WestBond’s public filings and third-party data. It is not affiliated with or endorsed by any newsletter or author, and contains no buy, sell, or hold recommendation. Company figures are from disclosures for the fiscal year ended March 31, 2026 and the quarter ended June 30, 2026; ownership and market data are as of mid-2026 and will change. Competitor scale figures and transaction values are approximate, drawn from public company disclosures and reported M&A terms, and are included for context rather than as precise financial data. Verify against the primary filings on SEDAR+ before making any decision.
SOURCES
• WestBond Industries — company website (westbond.ca)
• StockAnalysis — WBE profile, price & facts (stockanalysis.com/quote/tsxv/WBE)
• MarketScreener — major shareholders & management (marketscreener.com)
• WestBond — 2025 AGM results (GlobeNewswire, Aug 28 2025)
• WestBond Enterprises Corporation — MD&A & consolidated financial statements, FY ended Mar 31 2026 and Q1 ended Jun 30 2026 (SEDAR+, sedarplus.ca)
• Competitor profiles — company websites and investor disclosures: Magnera (NYSE: MAGN), Duni Group (Nasdaq STO: DUNI), Georgia-Pacific, Domtar/EAM, McAirlaid’s, Fitesa
• Air-laid consolidation history — publicly reported transaction records: Buckeye/Merfin (1997), Georgia-Pacific/Buckeye (2013), Glatfelter/Concert Industries (2010, C$237M); Concert CCAA filing (2004)