
Articles
See All
Aitenders (BIDS–CSE): A Profitable-ish French AI Company Sneaks Onto the Venture Board
First look. I bought some of the RTO financing at 58 cents. This is me kicking the tires out loud. I bought some stock as I know one of the key backers of the company—Wade Dawe, a very successful micro cap investor out of the Maritimes. Wade’s last deal, Kneat (KSI-TSX) was just bought out for $6+. That was a patient story that was a bit outside the box (medical software) but did well. This has the potential to be the same type of story.
Every so often a company shows up on the CSE that doesn’t look like the usual venture-board science project. Aitenders — trading as BIDS on the CSE since August 10 — is one of those.
It’s a French AI software company that sells to some of the biggest construction firms on earth, it did $2 million in real revenue last year, growing 84%, and — this is the part that made me sit up — it did that while almost breaking even. A net loss of $130,000 on $2 million in sales. On the venture board, a company that isn’t hemorrhaging cash is practically an exotic animal.
So let me walk you through what this thing actually does, how it gets paid, why the big engineering firms are signing, and some of the risks.
First, What They Actually Do
Here’s the problem Aitenders solves, in plain English.
When a giant infrastructure project goes out to bid — a nuclear plant, a rail tunnel, a transit line — the tender package that lands on a contractor’s desk isn’t a document. It’s a mountain of documents: Hundreds of files. Thousands of pages. Buried inside are the requirements, the deadlines, the legal obligations, the technical specs, and the traps — and if your bid team misses one, you either lose the bid or you win it and lose your shirt on a clause you didn’t catch.
Today, most construction companies attack that mountain the way they did in 1995: a small army of expensive experts, armed with Excel spreadsheets, Word docs, and email chains, reading everything by hand. It’s slow, it’s error-prone, and when a key person quits, all that institutional memory walks out the door with them.
Aitenders is an AI platform built to eat that mountain. Four pieces:
• Analyze — it reads the entire tender package at once, pulls out every requirement and risk, flags contradictions between versions, and tells the team whether the bid is even worth chasing.
• Write — it drafts the proposal response using the company’s own approved playbook and past winning bids.
• Deliver (Pilot) — after you win, it tracks all those contractual promises through construction so nothing slips.
• Knowledge — it remembers everything, turning every past bid into fuel for the next one.
The pitch is that it connects the whole lifecycle — from “should we bid?” all the way to “did we deliver what we promised?” — which the company argues no competitor does. And it’s wrapped in “hundreds of pre-configured AI agents” that do the grunt work in minutes instead of days.
How They Get Paid
This isn’t in the listing statement, so it’s worth spelling out. Aitenders sells per-user licences, tiered by how much of the platform you unlock, plus a recurring fee for infrastructure.
So it’s seat-based SaaS with a hosting component — not per-project, not one big enterprise site licence. That tells us exactly how this company grows: one more user at a time, inside one more business unit at a time.
The Thing That Might Actually Be a Moat
Here’s the angle I find most interesting—the core claim is that customer data never flows from the customer’s environment to an LLM vendor’s environment, under what the company calls a zero-data-retention LLM architecture, hosted in Europe (OVHcloud in France, Hetzner backup in Germany) with per-project isolation.
The platform is also LLM-agnostic — a number of the large customers run their own models, and Aitenders integrates with those. And, explicitly: Aitenders does not train models of its own.
THIS IS ABSOLUTELY KEY—sovereignty of data.
Read that carefully, because it cuts both ways.
The good half. LLM-agnostic is arguably more durable than owning your own models. It means Aitenders never has to defend a proprietary model against a frontier lab’s next release — it just swaps the engine.
And for the customer type that matters here, it’s the whole ballgame. Firms bidding on nuclear plants, defence-adjacent infrastructure and national rail are exactly the buyers who are terrified their competitive bid strategy leaks into somebody’s public model. In fact, many, (most?) companies have specific rules/internal laws forbidding that. Aitenders gets around that.
If that customer already runs its own LLM inside its own datacentre, Aitenders can plug into it. A Silicon Valley competitor built on an OpenAI API call structurally cannot.
The less good half. If the models aren’t theirs, and they don’t train, then the intellectual property isn’t in the AI. It’s in the plumbing and the workflow design. That’s a real asset — it is not the same asset the phrase “AI company” usually implies. Which brings us straight to the defensibility question.
What Would Stop Someone From Copying This
The company’s defensibility case rests on four arguments, and the quality varies:
• Each deployment becomes unique. The system structures and learns from that specific company’s proprietary data and workflows, getting more accurate and more valuable over time.
• Accumulated workflow design. Hundreds of agents and workflows informed by work with 150+ project teams — the argument being that no single contractor’s internal team has the cross-industry pattern library to replicate it.
• Construction firms don’t build software. Not a core competency, in the company’s phrasing, “even in the age of vibe coding.”
• ERP neutrality. The stated objective is to become the intelligence operating system for all project stakeholders and to stay ERP-neutral while doing it — the specific jab being that Procore or Trimble TRMB-NASD US$59 (two huge construction focused ERPs) can’t be ERP-neutral, because selling its ERP is the business.
There are also no patents. The technology is protected by trade secrets and by the relationships, not by IP filings.
The Customers Are the Real Story
The company says it’s deployed at three of the five largest construction companies in Europe, that its customers represent over $300 billion in combined market cap, and its own website waves around names like Veolia, Equans, Colas, Vinci, and Bouygues, plus marquee megaprojects — Hinkley Point C, Flamanville, Grand Paris Express, the Lyon-Turin tunnel.
While the listing statement itself names no customers, and I couldn’t independently confirm Aitenders’ exact role on any specific megaproject, the revenue is audited and real, and you don’t book $2 million selling enterprise software to Fortune-500-scale contractors on vapour. Something is genuinely working here.
The Concentration
One customer was roughly 40% of 2025 revenue. That’s a big, explicitly disclosed concentration, and it’s the single biggest risk in the story.
Two things soften it. The account is one of the logos shown on the company’s own home page — so it’s a large, creditworthy enterprise rather than a fragile one — and it sits on a three-year contract that is not up for renewal within the next twelve months.
That matters. You are not staring at a renewal cliff in 2026, and the 2026 forecast isn’t resting on a re-sign. It’s the most reassuring single fact in the risk section.
While this doesn’t remove the risk, it dates it. A three-year term on a revenue base this young means the concentration has a fuse, not a fix, and the termination-for-convenience language isn’t public — enterprise contracts usually have some.
The Number That Isn’t There
Aitenders does not—as yet—report net revenue retention.
That’s the gap that bothers me most. NRR is the single most diagnostic number for a land-and-expand story — it tells you in one figure whether existing customers buy more each year or quietly shrink.
For a company whose entire growth thesis is expansion inside accounts it already has, the absence of the expansion metric is a real hole. It’s a defensible choice for a brand-new issuer with a small customer base, where one renewal could swing a headline number.
But it means the core of the thesis is currently taken on faith. I’d expect it with the first full year of public reporting. If it still isn’t there, that tells you something too.
The Numbers — Better Than You’d Expect,
Smaller Than You’d Hope
The financials, straight (all Canadian dollars, audited):
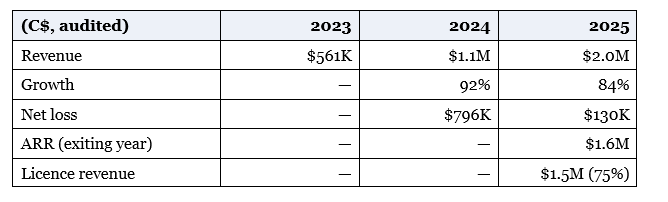
• Licence revenue is $1.5M, or 75% of the total — real recurring software, not consulting hours dressed up.
• 2026 revenue is projected at $4.8 million — but read that word carefully: projected, management’s own forecast, not in the bank.
• 21 employees.
For a microcap, that financial profile is unusually clean. A bootstrapped company — no venture capital in seven years — that got to $2 million with real margins tells you the founders are disciplined operators, not cash-burners.
The Land-And-Expand Math
This is where the arithmetic gets sobering, and where the seat-based pricing model above starts to matter.
From pilot completion to a signed multi-year contract runs 2–4 months. For enterprise construction software that is genuinely fast, and it’s a good sign — it means the product demonstrates value quickly rather than dying in a twelve-month procurement swamp.
But note the shape of the win. What Aitenders typically gets is adoption in production by one or more business units — not an enterprise-wide rollout. Sales and customer success then work that beachhead toward company-wide adoption, and in Europe that is a multi-year process.
So put the pieces together: seat-based pricing, deployment currently in under 1% of existing customers’ 6,000-plus business units, two to four months to land each new business unit, and a multi-year grind to convert a beachhead into a company-wide standard.
That is a genuinely enormous runway — and a slow drip. Getting from $2.0M to $4.8M in a single year requires a lot of business units saying yes in a short window. Which brings us to where they say yes.
North America Is Where the Story Has to Land
Europe is where the traction is. North America is where the growth thesis lives. The go-to-market here is more concrete than I expected going in, and it runs on two motions.
• Direct sales, primary. Several existing customers headquartered in Europe are also major players in the North American market, are already running Aitenders on North American projects, and their N.A. business units are the expansion target. Aitenders is onboarding staff in North America now.
• In-platform referrals. Customers can invite their partners and subcontractors to collaborate inside Aitenders. Those invited firms become free-trial-level users and drop straight into the sales funnel. The company reports this is already generating opportunities in North America.
Expanding into the North American arm of a client that already uses you in Europe is the shortest sales path in existence — the reference check is internal. And the referral mechanic is the closest thing in this whole story to a true network effect: every megaproject drags in dozens of subcontractors, and a platform that hosts the bid collaboration meets all of them, for free, with the customer doing the introduction.
There’s also a sleeper detail. The company says there are early signs that North American customers are willing to adopt at the enterprise level earlier than European ones—that’s just from conversations, not anything officially reported. If that holds, North America isn’t just the bigger market — it’s the faster one, and it would short-circuit the multi-year expansion grind described above.
What isn’t disclosed: no pipeline number, and no breakdown of how much of the $4.8M 2026 forecast comes from new North American logos versus expansion of existing European accounts. Note too that “onboarding staff in North America” is present tense — the team isn’t built yet. So the forecast stands as an unaudited projection unsupported by any disclosed pipeline.
How It Came Public
Aitenders came public through an RTO—Reverse Take Over—of a shell company called eXeBlock (old ticker XBLK.X), a dormant CSE listing with no business, whose only real value was the listing itself and a bit of cash. Aitenders’ shareholders reversed into it, renamed it, and took control. The deal closed July 31; trading started August 10.
This is a totally normal, legal way for a small company to get public without the cost of a full IPO. The first public raise was just a $2.4 million private placement at $0.5833 a share, run by a Halifax based boutique called Numus Capital. So the “validation” a traditional IPO gives you isn’t here. You’re doing your own diligence. That’s the whole point of this report.
The Cap Structure, And Why The Float Is Tiny
• Market cap: ~C$35 million at $0.5833.
• ~65 million shares out (67.5M fully diluted), plus 2.56M warrants around $0.67.
• Insiders own 68.9% — CEO Geoffrey Guilly alone holds about 56%. Institutions 9%, employees ~4%. The institution is Torrent Capital, which is essentially controlled by Wade Dawe, whom I have known for years. He is a very successful micro-cap investor, and his last deal was Kneat (KSI-TSX), an Irish based biotech software company that went from 40 cents to $6 over 10 years—and was successfully bought out.
• Which leaves a public float of roughly 12% — call it $4 million of actual tradeable stock.
The People
The board is genuinely impressive for a company this size, and that’s a real tell — serious people don’t lend their names to junk.
CEO Geoffrey Guilly is a construction-finance lifer — former APAC CFO at Systra, ran India for Egis (1,800 people), NYU MBA. CTO Julien Subercaze has a PhD in AI and 40-plus research papers — a real technologist, not a “chief AI officer” in title only. Around them: a former AECOM chief risk officer, the CIO of EllisDon (one of Canada’s biggest builders), a former TELUS president, and — importantly — a former Procore sales leader who grew that company’s revenue from $1M to $50M. If you’re selling construction SaaS in North America, that’s exactly the Rolodex you want.
Two items in the governance file are worth working through rather than glossing over.
One more wrinkle worth knowing: the placement agent, Numus, has one of its own executives sitting on the board. Disclosed, not unusual for this corner of the market, still a related-party relationship to keep in view.
What Could Go Wrong
• The 40% customer is dated, not defused. A three-year contract with no renewal inside twelve months buys real time. It doesn’t change the fact that roughly two-fifths of revenue sits in one account, on terms nobody outside the company can read.
• No NRR. The expansion metric for an expansion story isn’t disclosed. Until it is, the core of the thesis is unmeasured.
• The valuation isn’t cheap. $35M on $2M of 2025 sales is ~17x revenue, ~22x ARR. On the projected $4.8M it’s ~7x forward — reasonable for an 84% grower if they hit it. They have to hit it.
• The moat is orchestration, not IP. No patents, no proprietary models, no training. What Aitenders owns is workflow design accumulated across 150+ project teams plus the learning inside each deployment. That’s sticky and it’s real — it is not a patent, and it doesn’t protect a single customer they haven’t won yet.
• The cash position is an assertion, not a runway number. The headline “available funds” of ~$7.9M includes roughly $3.1M of projected revenue rather than cash raised, so real cash is closer to $4.8M against a similar-sized spending plan. The $754K loan has been refinanced per the SEDAR filings — a genuine improvement that removes a hard near-term claim on cash.
I don’t worry much about the cash position because I know Wade can raise money at will—just a question of price, as always.
• North America is staffing up, not staffed. The go-to-market is credible, but the team is being onboarded right now and the whole growth thesis rests on it landing.
• It’s a shell RTO with a 12% float. Illiquid, volatile, and you’re the diligence department.
The Bottom Line
What’s solid.
1. Audited revenue growing 84% with 75% of it licence-based.
2. Near-breakeven economics on a bootstrapped balance sheet.
3. A refinanced loan that removes a hard near-term claim on cash.
4. An anchor customer locked for three years.
5. A credible architectural wedge in data sovereignty that a US-hosted competitor structurally can’t match.
6. A North American go-to-market built on customers who already use the product elsewhere, plus a referral mechanic with genuine leverage.
7. And a board that has actually sold construction software on this continent.
What isn’t measurable yet.
1. No net revenue retention.
2. No runway stated in months.
3. No pipeline figure.
4. No breakdown of the 2026 forecast between new North American logos and European expansion.
5. No named customer.
6. Every one of those is a normal choice for a brand-new issuer — and every one of them means the load-bearing numbers in this thesis are taken on trust.
7. It’s also worth being precise about the sovereignty pitch: it’s a zero-data-retention, LLM-agnostic architecture, which is a strong commercial wedge, but it isn’t the same thing as owning the AI.
So: strip away the buzzwords and here’s what you’ve got. A disciplined, bootstrapped French software company with real revenue, 84% growth, near-breakeven economics, a credible angle on data sovereignty, blue-chip customers, and a board that knows how to sell construction software in North America — that just came public cheaply and quietly onto the CSE with a tiny float.
That’s a legitimately interesting setup. It is not a sure thing. The customer concentration, the “trust me” projections, the undisclosed retention, the thin cash cushion and the venture-board plumbing are all real. This is a watch-it-closely, size-it-small, ask-hard-questions kind of stock — the sleeper that could re-rate if the North American land-and-expand actually lands, and could just as easily sit dead or drift if it doesn’t.
I did buy some of the IPO, but it is not in any subscriber portfolio. I’ll be watching the first two quarters of public reporting very closely. Take it all FWIW.
NOTE–this story was written by me and my best friend Claude(AI)
This is research and opinion, not investment advice — I’m not your advisor, and I don’t own BIDS. It’s a brand-new, thinly-traded microcap that came public via a shell reverse-takeover; that’s a higher-risk structure by nature. Company performance claims (customer names, ROI figures, project references, product and strategy descriptions) originate with the company and are not independently verified. Do your own homework on the filings before you buy a single share.